By Tony O. Lawson
Much of Wall Street’s attention remains concentrated on artificial intelligence and the companies building its infrastructure.
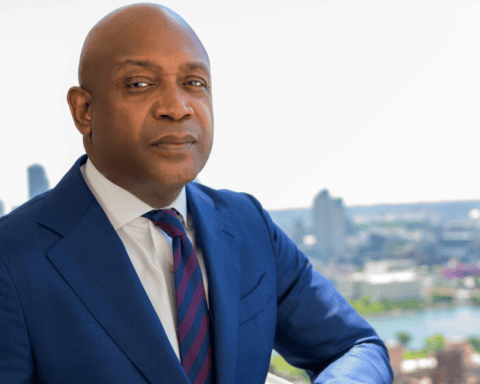
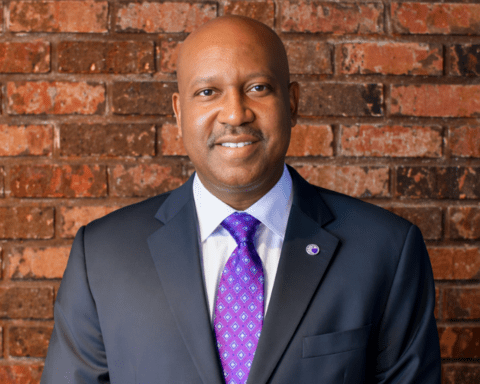
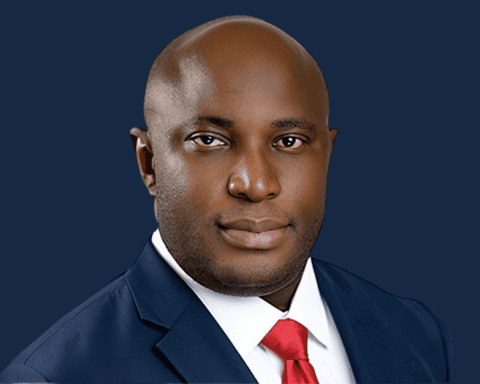
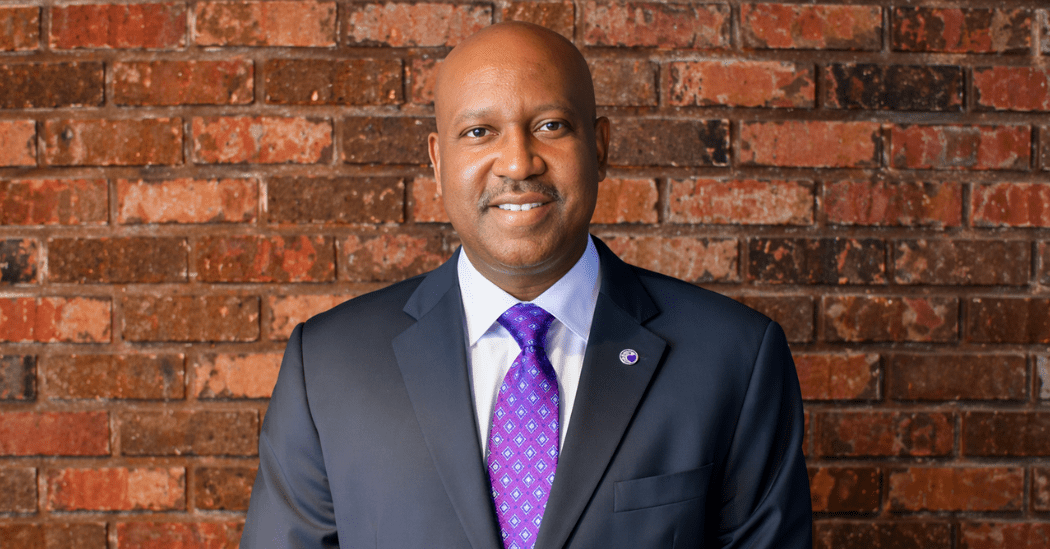
Randell Cain, founder and chief investment officer of Kerusso Capital Management, is finding opportunities in businesses receiving considerably less attention.
The Winston-Salem, North Carolina-based investment firm reported surpassing $300 million in total firm-wide assets as of June 30, 2026. Cain has managed investments since 1997, developing an approach centered on identifying companies whose market valuations underestimate their financial strength and long-term prospects.
That discipline is particularly relevant in a market shaped by concerns about AI disruption, changing economic conditions, and significant differences in performance across investment styles.
As of late September 2026, the Russell 1000 Value Index had gained nearly 21%, compared with approximately 7% for the Russell 1000 Growth Index, according to J.P. Morgan Asset Management.
Changes to index composition explain a significant portion of that divergence, complicating comparisons between the two investment styles.
Kerusso’s investment process focuses on whether a company’s share price accurately reflects its underlying financial performance and long-term earnings potential.
Finding Value in Software Companies
Enterprise software has become one of Kerusso’s areas of interest.
Concerns that generative AI could disrupt established software businesses have contributed to substantial share-price declines.
Over recent quarters, Kerusso purchased or increased positions in Autodesk, Adobe, Accenture, and Salesforce. Cain said their shares had fallen approximately 20% to 40%, with some experiencing steeper declines.
Their operating results, however, had generally held up better than their stock prices.
Adobe provides an example. In its fiscal third-quarter 2026 filing, the company reported revenue of $6.76 billion, up 13% from $5.99 billion a year earlier. Net income increased approximately 3%, from $1.77 billion to $1.83 billion, while earnings per share rose 11%, aided by share repurchases.
Those figures illustrate the distinction between current financial performance and investor expectations about future disruption.
AI still presents competitive risks, including potential pressure on software pricing, customer retention, and established business models.
Companies with established customer relationships and substantial financial resources may be positioned to incorporate AI into their products, potentially strengthening their competitive positions.
Kerusso’s investment assessment centers on whether the market has discounted those businesses more heavily than their fundamentals warrant.
The Investment Case Beyond AI Infrastructure
The first phase of the artificial intelligence investment boom has rewarded companies supplying semiconductors, computing equipment, and data center infrastructure. The next test will be whether businesses across the broader economy can turn that investment into measurable productivity gains and stronger earnings.
Kerusso’s analysis separates AI adoption into three stages: infrastructure development, integration into existing technology products, and deployment across industries such as financial services, manufacturing, and consumer businesses.
That final stage presents a different set of investment opportunities. Established companies may improve operating margins, automate routine processes, and expand services without bearing the full cost of developing foundational AI technology.
“The other nine or ten sectors are the ones that are really going to reveal if AI is worth all the hype,” Cain said during an interview with Shoppe Black.
The distinction also informs how Kerusso evaluates valuations. Expectations for future AI growth have pushed some technology companies to substantial premiums, while concerns about disruption have weighed on established businesses with continuing revenue and cash flow.
The firm is examining both sides of that divergence, including companies positioned to benefit from AI adoption and businesses whose competitive risks may already be reflected in their share prices.
“I’m not the kind of a visionary investor,” Cain explained. “I need a little more meat and potatoes on my plate.”
Why Kerusso Invested in Micron and Oracle
Kerusso’s investment decisions illustrate how the firm evaluates changes in industry conditions.
During 2026, the firm established a position in Micron Technology and increased exposure to Oracle and Adobe.
Micron initially presented a familiar concern: the semiconductor industry’s historical cyclicality.
Chip manufacturers can appear inexpensive when trading at low earnings multiples. Historically, those valuations have sometimes coincided with peak profitability, before additional production capacity pressures prices and margins.
AI-related demand has complicated that pattern.
Manufacturers are allocating capacity toward higher-value chips used in AI infrastructure, potentially extending industry cycles and changing earnings expectations.
“You can know a lot and know too much,” Cain said, reflecting on his earlier hesitation.
The changing demand environment ultimately influenced Kerusso’s decision to establish a position.
Oracle presented a different opportunity.
Concerns about debt, data center spending, and the execution of major infrastructure projects had weighed on investor sentiment. Kerusso assessed the company’s valuation as unusually low relative to its fundamentals and growth prospects.
Both investments reflect the firm’s willingness to reconsider established assumptions when business conditions change.
Kerusso uses SWOT analysis, examining strengths, weaknesses, opportunities, and threats, to evaluate investment candidates.
During market rallies, investors may place greater emphasis on a company’s strengths. During declines, attention often shifts toward weaknesses and potential risks.
Kerusso’s process considers all four factors regardless of prevailing market sentiment.
Looking Beyond Technology
Market concentration has created potential opportunities across industries receiving less investor attention.
Technology represented 18.6% of the Russell 1000 Value Index as of June 30, 2026, compared with 3.7% two decades earlier, according to State Street Global Advisors.
The increase illustrates how technology has become an increasingly important component of value-oriented benchmarks.
Kerusso maintains overweight allocations to financials, energy, consumer discretionary, and materials, alongside a marginal overweight in technology.
In financial services, opportunities include consumer finance, insurance, and asset management companies that can use AI to improve customer service and operating efficiency.
Energy is another significant allocation.
Kerusso owns exploration and production companies Devon Energy and EOG Resources, alongside Cheniere Energy and Marathon Petroleum.
The capital discipline of Devon and EOG is central to Kerusso’s investment rationale. Cain said both companies can operate profitably with oil prices around $60 to $70 per barrel.
Moderating energy prices, inflation, and interest rates could eventually improve household purchasing power, benefiting selected consumer discretionary businesses.
The firm’s holdings in that sector include Restaurant Brands International, Lowe’s, Home Depot, TJX, and Tapestry.
These allocations reflect Kerusso’s assessment of relative valuations, industry conditions, and potential earnings growth across the market.
Managing Risk Through Valuation Discipline
Kerusso’s approach to risk management begins with the price paid for an investment.
The firm seeks companies with established businesses and financial fundamentals whose shares trade at valuations that may underestimate their long-term earnings potential.
“We basically purchase our downside when we’re buying stocks,” Cain said.
The strategy also emphasizes portfolio discipline.
Kerusso generally holds investments for three to five years, with annual turnover of approximately 20% to 30%.
The firm reassesses positions as valuations change, trimming holdings when their prices approach what it considers fair value and reallocating capital toward opportunities offering more attractive potential returns.
The emphasis on downside protection reflects Kerusso’s stated investment objective. Actual investment results depend on market conditions, security selection, and portfolio construction.
Positioning for the Next Market Cycle
Further opportunities could emerge as investors reassess companies outside the most prominent AI-related investments.
Software businesses adapting to technological change, financial institutions improving operating efficiency, and companies positioned for shifts in economic conditions all feature in Kerusso’s outlook.
The firm’s investment philosophy centers on identifying where expectations have become disconnected from fundamentals and adjusting positions as those relationships change.
With technology accounting for a growing share of both growth and value benchmarks, maintaining the flexibility to invest across sectors remains an important part of that approach.
For Kerusso, the process involves continually reassessing which businesses offer the most attractive combination of valuation, financial strength, and long-term potential.
Editor’s Note: This article is based on an October 29, 2026, interview with Randell Cain of Kerusso Capital Management and publicly available market research and financial filings. Portfolio holdings reflect information provided during the interview and may change. The article is for informational purposes and does not constitute investment advice. References to individual securities are not recommendations to buy or sell. Past performance does not guarantee future results.